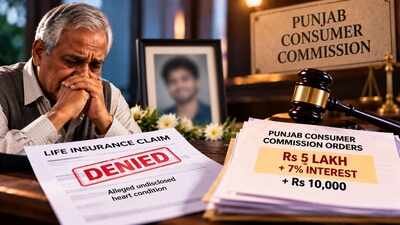
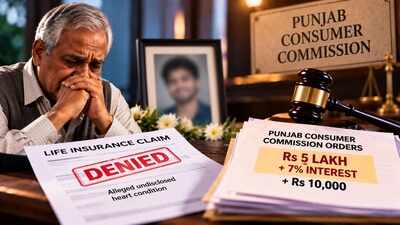
Your child takes life insurance, and after his death the insurer denies the claim on the basis that your son hid a pre-existing condition. What happens then?In one such case, the District Consumer Disputes Redressal Commission, Sri Muktsar Sahib, has directed the Life Insurance Corporation of India (LIC) to pay Rs 5 lakh to the nominee of the deceased policyholder.
What the case is about
The father and nominee of the deceased son, approached the consumer commission after LIC refused to honour a life insurance claim following his son’s death.The son had obtained an LIC policy in April 2022. The policy carried a maturity date of 2043 and provided a sum insured of Rs 5 lakh. He was paying a monthly premium of Rs 2,290 plus GST. The complaint stated that total premiums of Rs 36,000 had been paid.However, the son died on August 4, 2023, while the policy was still in force. The complainant’s case was that his son died of a heart attack and that, after his death, the required documents were submitted to LIC to claim the insured amount. LIC eventually repudiated the claim in January 2024.The insurer’s defence was based on alleged suppression of medical information. LIC argued that the policy had not completed three years when the insured person died and that scrutiny of the claim had revealed that he had not disclosed an earlier heart condition while obtaining the insurance cover.According to LIC, the man had suffered from ASD/VSD and had undergone an ASD/VSD closure and Post Fontan procedure in 2008. LIC relied on a discharge summary from Jindal Heart Institute and Maternity Centre, Bathinda, dated April 2023, which referred to Atrial Flutter/CHD and the earlier procedure. LIC maintained that these were material medical facts which should have been disclosed.The insurer also relied on medical and bed-rest documents from 2023 and its claim scrutiny records.
Why the father won the insurance claim
The Commission’s central concern was not simply whether the insured person had ever undergone a medical procedure. It was whether LIC had actually established, with the evidence placed before the Commission, that he had concealed a relevant pre-existing medical condition when the policy was obtained.The evidence relating to the proposal form created the first major problem for LIC.The Commission examined two proposal forms produced by the insurer. The first contained only two pages and did not carry the man’s signature or the date on which it had allegedly been obtained or submitted.The second document was described as the complete proposal form. But the Commission noted that it showed a date of May 22, 2022, whereas the insurance policy itself had already been issued on April 28, 2022.The Commission therefore questioned how a proposal form obtained after the policy had been issued could establish what information the insured had disclosed when applying for the policy.There was another significant gap. LIC’s repudiation letter referred to a proposal form dated May 30, 2022, in which Sukhdev Singh had allegedly answered the health questions as “No”. But the Commission found that no proposal form dated May 30, 2022 had actually been placed on the record.The Commission further observed that almost all the columns in the second proposal form were blank apart from the signature and date of the deceased man.The medical evidence also did not establish what LIC needed to prove.The Jindal Hospital discharge summary and other treatment papers relied upon by LIC related to the period between April 15 and April 17, 2023, nearly a year after the insurance policy had been issued.The Commission specifically noted that LIC had not produced even a single medical document from a hospital or doctor dating from before April 28, 2022 to establish the alleged condition at the time the policy was obtained.LIC had also referred to an ASD/VSD closure and Post Fontan procedure allegedly performed in 2008. But, again, no medical record documenting that procedure was produced. The Commission observed that even if the procedure had taken place in 2008, it would have been around 14 to 15 years before the policy was purchased.The Commission also took note of the fact that the deceased was 30 years old and had been working with a company from January 5, 2022. It observed that he might have undergone a medical check-up or obtained a fitness certificate before joining service. LIC had also failed to place the insurance policy and its terms and conditions on record.The Commission referred to a National Consumer Disputes Redressal Commission decision concerning “silent diseases”, observing that a person may not necessarily be aware of a condition until it aggravates and symptoms become apparent. It also referred to a Punjab and Haryana High Court judgment concerning repudiation of insurance claims.After considering the evidence, the Commission concluded that LIC had wrongly and illegally repudiated the death claim, amounting to deficiency in service. It set aside the January 29, 2024 repudiation letter.LIC has now been directed to pay Rs 5 lakh, after deducting any premium amount that may already have been refunded to Roop Singh on an ex-gratia basis. The amount will carry 7% annual interest from January 29, 2024 until realization. LIC must also pay Rs 10,000 towards compensation and litigation expenses. The order has to be complied within 45 days of receiving its copy.According to Jyoti Sinha, Partner, Khaitan & Co, this ruling adds to a growing line of cases on ‘silent diseases’, conditions a person may have had but did not know about at the time of taking up an insurance policy.“In this case, Roop Singh, father and nominee of the deceased policyholder Sukhdev Singh, filed a complaint after LIC repudiated his claim for the assured sum of Rs 5,00,000 following Sukhdev’s death from a heart attack in 2023. LIC’s grounds for repudiation were that the deceased had undergone an ASD/VSD closure and Post Fontan procedure approximately 14 years prior to the policy and had failed to disclose this in his proposal form,” Sinha explains.“The Commission held that an insurer cannot repudiate a claim merely by pointing to a childhood surgical procedure conducted 14 years before the policy was obtained, particularly where the insurer fails to discharge the evidentiary burden of establishing that the condition persisted despite the heart procedure conducted during the policyholder’s childhood and that knowledge of such condition was deliberately concealed,” she tells TOI.Significantly, the Commission observed that LIC failed to produce any medical records from the time of the 2008 procedure or predating the policy’s issuance in 2022, relying instead solely on hospital records from 2023.“The ruling thus solidifies that where an insurer seeks to repudiate a claim on grounds of non-disclosure, it must bring proper proof. Old medical history, without evidence that the policyholder knew and deliberately hid is not sufficient to reject the claim,” she concludes.
✍️ Vikrant Kharwar
Vikrant Kharwar is the Founder and Editor of News Us Media. He writes about trending news, sports, entertainment, technology, and viral stories. His goal is to make news simple, informative, and easy to understand for readers across the United States and around the world.